U.S. expat tax & practical financial support
Living abroad. Still connected to the U.S.
Your family, career and home may be overseas. U.S. tax returns, foreign-account reporting and financial paperwork can still follow you. We help you understand what applies and stay organized.
Cross-border questions deserve more than a generic tax-software workflow.
One international life. Two practical needs.
Less U.S. paperwork. More peace of mind abroad.
We focus on two connected needs: preparing U.S. tax filings correctly and helping Americans abroad organize the routine U.S. financial obligations that don’t disappear when they move.
Service / tax
U.S. tax preparation for Americans overseas
CPA-led return preparation with attention to foreign earnings, accounts, investments, families and filing history.
- Federal Form 1040, filing status and relevant schedules
- Foreign income, credits and exclusions
- FinCEN FBAR and IRS foreign-asset reporting assessments
- Foreign company ownership and specialized forms (including Form 5471) when relevant
- Prior-year filing and notice review
Service / ongoing support
U.S. bills, payments & financial administration
Practical assistance for the bills and financial paperwork you still have in the U.S., even when you live several time zones away.
- Bill tracking and payment-date reminders
- Payment coordination with client approval
- Statements, notices and account paperwork
- Simple financial calendars and recordkeeping
U.S. tax for expats
File with the full cross-border picture in view.
U.S. citizens and many green-card holders may have filing requirements even after moving abroad. We prepare the U.S. return, identify additional disclosures and make the process understandable.
Your quote is based on the years, forms and complexity involved—not a surprise list of add-ons later.
01 / Individual returns
Federal tax preparation
Form 1040, wages, self-employment, investments, foreign pensions and filing-status questions, as relevant to your facts.
02 / Cross-border relief
Foreign income & double-tax rules
Foreign tax credit (Form 1116), foreign earned income exclusion (Form 2555) and housing-related provisions where applicable.
03 / Reporting
Foreign accounts & assets
FinCEN FBAR (Form 114), Form 8938 and screening for foreign-company or investment disclosures such as Forms 5471 and 8621 when relevant.
Not up to date?
Prior years deserve a clear plan, too.
Missed a return, received an IRS notice or unsure whether you should have filed an FBAR? We can help organize the facts and determine whether tax-return preparation or referral for a specialist compliance procedure is appropriate.
Ask about your filing historyWhat surprises Americans overseas
Three filing facts worth knowing early.
Moving to Germany changes your address. It does not, by itself, switch off U.S. tax and reporting rules.
Form 1040
Your tax home can be abroad.
U.S. citizens generally remain subject to U.S. tax rules on worldwide income, with filing determined by the applicable thresholds and circumstances. Credits and exclusions can help prevent double taxation.
$10,000
Across accounts, not per bank.
A U.S. person generally must file a FinCEN FBAR (Form 114) if the combined maximum value of reportable non-U.S. accounts exceeds $10,000 at any time during the year. Jointly held accounts can count.
Two systems
FinCEN is not the IRS.
The FBAR is filed separately with FinCEN. IRS Form 8938 may also be required with a tax return when the higher, situation-dependent foreign-asset thresholds apply. One does not replace the other.
A familiar example
An American mom moves to Germany with her German husband.
They open a joint German bank account, she takes time away from work after having a baby, and the family starts saving through a local investment account. What should they check on the U.S. side?
- Whether she has a Form 1040 filing obligation and which married filing status applies
- Whether their German accounts trigger a FinCEN FBAR or IRS Form 8938
- Whether foreign funds, pensions, gifts or family benefits need special review
- Whether a German GmbH or UG ownership interest raises Form 5471 questions
- Whether a child born in Germany acquired U.S. citizenship and needs citizenship documentation
This is a hypothetical illustration, not a conclusion that every item must be filed.
For expats who own a business
Own part of a German GmbH or UG? Ask about Form 5471.
A U.S. citizen with certain ownership or officer/director relationships to a foreign corporation may have to file IRS Form 5471 with their U.S. income tax return. Some reporting categories have a 10% voting power or value ownership trigger; control, attribution rules, transactions and the specific filing category also matter.
Certain failures to file a complete, timely Form 5471 can carry an initial $10,000 penalty. Not every German business interest requires the form, but it is worth checking before the annual U.S. return is filed.
Entity classification and filing categories require individual review. A foreign spouse owning a company does not, by itself, establish that the American spouse must file.
Support beyond tax season
The U.S. bills don’t stop when you move abroad.
A U.S. home, bank account, insurance policy, subscription or tax notice can create work from thousands of miles away. We help you stay organized, spot deadlines and coordinate the administrative steps.
Available as a separately scoped service, whether or not we prepare your tax return.
01 / Never lose track
Bills & due dates
Organize recurring U.S. bills, track upcoming due dates and maintain a clear schedule of what needs attention.
- Utilities, property-related bills and insurance
- Credit cards, subscriptions and other recurring charges
- Reminders and exception follow-up
02 / Keep control
Bill payment coordination
Prepare a payment list, review supporting bills and help coordinate payments through your existing accounts and service providers.
- Client review and approval before payment
- Confirmations and payment records
- Follow-up on disputed or unusual charges
03 / Make sense of mail
U.S. notices & paperwork
Sort digital statements, notices and administrative requests, identify their next steps and keep supporting records together.
- Bank, lender, insurance and vendor communications
- Document lists and response deadlines
- Coordination with your U.S. contacts as authorized
04 / Stay organized
Ongoing financial admin
Maintain an organized view of U.S. obligations so routine tasks don’t become last-minute problems.
- Monthly bills and financial-document check-in
- Simple cash-flow and due-date summaries
- Year-end document collection for tax season
Who this is for
Made for people whose lives span borders.
Whether you’re newly abroad or have built a life overseas, having one organized point of contact for U.S. paperwork can make a difference.
- U.S. citizens and green-card holders living in Germany, Europe or elsewhere
- Employees, freelancers, retirees and internationally mobile families
- People with U.S. property, bank accounts, ongoing bills or administrative obligations
- Americans catching up on returns, foreign reporting or documentation
- Families with a non-U.S. spouse or changing cross-border circumstances
A straightforward process
Clear scope. Organized documents. Direct communication.
No need to know every form, deadline or system before contacting us. We start with your circumstances and agree on the work before moving forward.
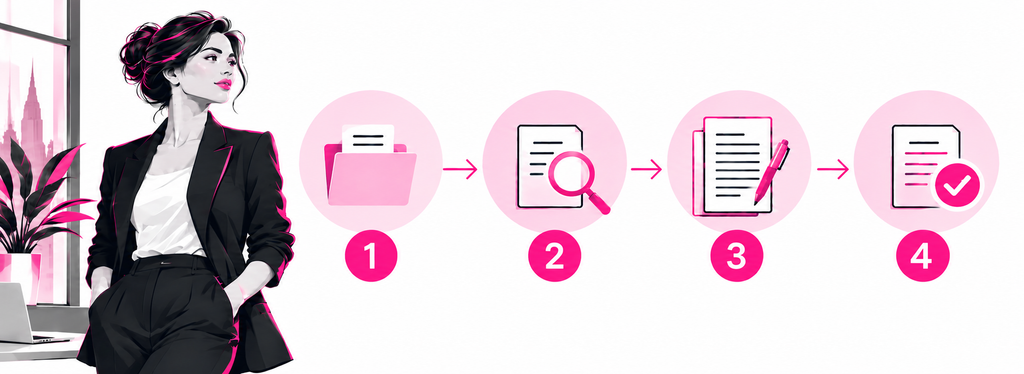
Tell us what you need
Where you live, which U.S. obligations remain and the tax years or bills causing concern.
Confirm the scope
We outline the services, information needed, fee basis and what remains your responsibility.
Review & coordinate
We work through documents, prepare filings or build a practical recurring admin routine.
Close out & stay ready
Receive the agreed deliverables, records and next-step reminders or ongoing support.
Common questions
Moved abroad? Here are the details that can matter.
Especially for American families in Germany, a new household, new bank account or change in work status can raise U.S. reporting questions.
I moved to Germany and pay German income tax. Do I still file Form 1040?
Often, yes. U.S. citizens generally report worldwide income when a U.S. filing requirement applies, even if they live and pay tax in Germany. Depending on the facts, Form 1116 (foreign tax credit) or Form 2555 (foreign earned income exclusion) may reduce U.S. tax. German tax paid does not automatically eliminate U.S. filing.
My husband is German and does not have a U.S. Social Security number. Must we file jointly?
Not necessarily. An American married to a nonresident alien spouse may generally file as married filing separately, subject to the applicable rules. In some circumstances, both spouses can elect to file jointly, but that normally brings both spouses’ worldwide income into the U.S. return while the election applies. We review the election before treating joint filing as the default.
I am home with the kids and have little or no income. Do I still need to file?
A Form 1040 requirement depends on filing status, income and special rules, including self-employment income; citizenship alone does not mean everyone must file a tax return every year. But separate foreign-account reporting may still apply even if no Form 1040 is due. The year of a move and any U.S. income also deserve a check.
We opened a joint German bank account. Does my German spouse’s account count for my FBAR?
If you are a U.S. person with a financial interest in a German account, including a joint account, it can be reportable. The FinCEN FBAR threshold is based on the combined maximum value of all your reportable foreign accounts exceeding $10,000 at any time, not $10,000 for each account. A spouse who is not independently a U.S. person does not become an FBAR filer solely through the marriage.
Is the FinCEN FBAR the same as IRS Form 8938?
No. FinCEN Form 114 (FBAR) is a separate electronic Treasury filing. IRS Form 8938 is generally attached to an income tax return when its own higher thresholds and filing conditions are met. For qualifying taxpayers living abroad who do not file jointly, an often-relevant Form 8938 threshold is more than $200,000 at year-end or $300,000 at any point; other thresholds apply to joint filers and different circumstances.
Will Germany and the United States tax my salary twice?
Not necessarily. Form 1116 may allow a credit for eligible German income taxes, while Form 2555 may permit qualifying foreign earned income to be excluded. The two approaches have different effects and restrictions; choosing one without considering the other, or the U.S.–Germany treaty, can be costly. They do not guarantee a zero U.S. liability.
We had a baby in Germany. Does our child need U.S. paperwork?
A child born in Germany to a U.S.-citizen parent may acquire U.S. citizenship at birth if the statutory conditions are met. A Consular Report of Birth Abroad (CRBA) is a way to document citizenship acquired at birth, and a U.S. passport and Social Security number may also be relevant. Tax benefits depend on separate eligibility and identification rules.
How do German Kindergeld or Elterngeld affect my U.S. return?
German child and parental benefits should be identified during the tax review rather than omitted automatically. Their U.S. treatment depends on the particular benefit, applicable law and treaty provisions, and individual facts. We also check filing status and any relevant child-related U.S. credits.
Can I buy German ETFs, mutual funds or other investments without extra U.S. forms?
Some non-U.S. mutual funds and ETFs can be treated as passive foreign investment companies (PFICs) for U.S. purposes. That may lead to complex tax calculations and IRS Form 8621 reporting. Have the investment reviewed before assuming that a German tax-efficient product is simple on a U.S. return.
My German husband and I own a GmbH or UG. Do I need to file IRS Form 5471?
Possibly. Form 5471 is an information return for certain U.S. persons who are shareholders, officers or directors of corporations organized outside the United States. Some reporting categories are triggered by acquiring or holding 10% or more of voting power or value, while other categories depend on control, U.S.-shareholder status, and ownership attribution. It can apply even if the company is not profitable or pays no dividend. A German GmbH or UG should first be analyzed under U.S. entity-classification rules. Certain missed or incomplete filings can carry an initial $10,000 penalty. Your German spouse owning a business does not automatically mean you personally must file; the actual ownership and attribution rules need checking.
What if I run a German freelance business or own a foreign partnership instead?
The reporting form depends on how the business is classified for U.S. tax purposes. Form 8858 can apply to certain foreign disregarded entities or branches; Form 8865 can apply to certain foreign partnerships; and Form 5471 can apply to certain foreign corporations. These are not interchangeable, and they may be separate from Schedule C, self-employment tax and German filing requirements.
Is Form 5471 the same as Form 5472?
No. Form 5471 concerns certain U.S. persons’ interests in or relationships with foreign corporations, such as some German GmbHs. Form 5472 concerns certain reportable related-party transactions involving foreign-owned U.S. entities and some foreign corporations engaged in a U.S. trade or business. The two forms serve different purposes, and neither should be assumed to apply just because a spouse is German.
What about a German workplace pension or private retirement contract?
German pension and retirement arrangements can have different U.S. tax and foreign-account or foreign-asset reporting consequences depending on their legal form and ownership. No single rule applies to all German pensions, insurance contracts and investment products. We review the documents and coordinate specialist advice when required.
What if I freelance in Germany? Will I owe Social Security in both countries?
The U.S.–Germany Social Security totalization agreement can coordinate coverage and may prevent duplicate contributions for qualifying employment or self-employment. The outcome depends on the work arrangement and applicable certificate of coverage; it should not be assumed from residence alone.
My German relatives gave us money or left me an inheritance. Is there a U.S. form?
A U.S. person who receives certain large gifts or bequests from non-U.S. individuals or foreign estates may need to file Form 3520, even when the receipt is not itself ordinary taxable income. The commonly relevant aggregate threshold for gifts from nonresident alien individuals or foreign estates is over $100,000, subject to specific rules.
I left a U.S. state. Do I still need to file a state tax return?
Possibly. State rules differ, and a move abroad does not always end state residency or source-income filing requirements. We check the former state of residence, domicile facts, remaining property, employment and other U.S. connections.
When are my U.S. return and FinCEN FBAR due?
Calendar-year individual federal returns are generally due in April. Eligible taxpayers living abroad typically receive an automatic two-month filing extension (usually until June 15), but interest on unpaid tax may begin from the ordinary April due date. The FBAR has a separate April deadline with an automatic extension to October 15. Confirm the dates for the applicable tax year.
Is FinCEN beneficial ownership reporting the same thing as my personal FBAR?
No. Personal foreign-account reporting (FBAR) and business beneficial ownership information (BOI) reporting are different. Under FinCEN rules effective August 14, 2026, U.S.-formed companies are exempt from BOI filing, while certain foreign-formed companies registered in the United States may still have obligations. The personal FBAR rules remain separate.
Can you actually take care of my U.S. bills while I live overseas?
We can organize bills, track deadlines, prepare a payment schedule and coordinate client-approved actions with providers. You keep control of accounts and authorize payments. Any service outside administrative coordination would require a separate review and written agreement.
Do I need to be a tax client to get bill and paperwork support?
No. U.S. financial administration can be discussed as a standalone service, with a separately defined scope and fee arrangement.
What if I missed several years of tax filings?
We can help organize your filing history and prepare returns where appropriate. If a formal compliance procedure or legal representation is needed, we can coordinate with suitable specialists.
Can you file my German or other non-U.S. tax return?
Our tax service focuses on U.S. filing obligations. Where helpful, we can coordinate with your local tax adviser; preparation of local-country returns is not included unless expressly agreed with a qualified provider.
What does it cost?
Tax preparation is quoted based on the years, forms and complexity involved. Recurring administrative support is scoped around the volume of bills, tasks and desired frequency. We confirm the scope and pricing before engagement.
Official guidance
IRS: Americans abroad · IRS: Nonresident spouse · FinCEN: FBAR · IRS: Form 8938 · IRS: Form 5471 · IRS: Form 8858 · IRS: Form 8865 · IRS: Form 8621 · IRS: Foreign gifts · SSA: Germany agreement · State Department: Children born abroad · FinCEN: BOI
General guidance reviewed October 29, 2026. Rules and thresholds can change; the analysis for an individual depends on the tax year and circumstances.
Make U.S. matters manageable
Tell us what’s still on your U.S. to-do list.
Whether the priority is a tax filing, past-due paperwork or a monthly collection of U.S. bills, let’s identify the work and the next steps.
Prefer to read first? Download the U.S. Expat Tax Starter Guide